
Key Takeaways
- DSCR lender case study content turns closed investor deals into public, verifiable proof that your team knows how to structure rental property financing.
- 53% of B2B marketers say case studies and customer stories produce their best results, second only to video, according to the Content Marketing Institute.
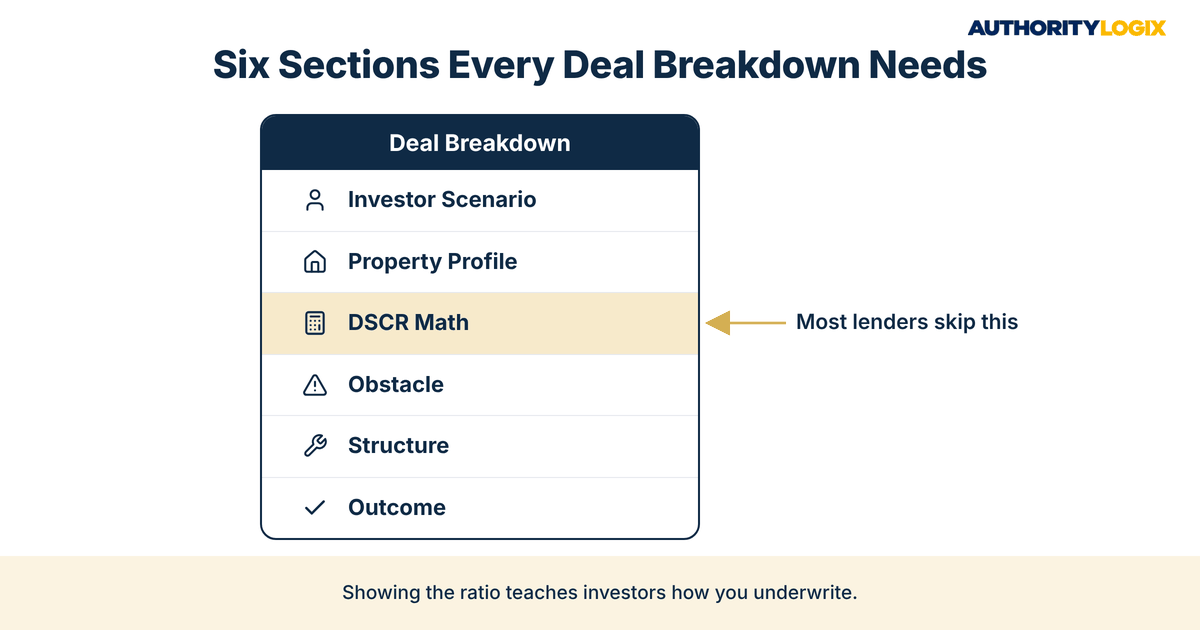
- The strongest format is the deal breakdown: investor scenario, property profile, DSCR math, the obstacle, the structure, and a factual outcome.
- Compliance comes first. Anonymize the borrower, get written consent, and keep rates and payment terms out unless compliance has approved the disclosures.
- Distribution to investors, brokers, and search is what turns one breakdown into a lead source.
- Your closed deals are already the evidence. DSCR lender case study content is the infrastructure that lets the market see it.
Table of Contents

DSCR lender case study content is the most direct way a lender can show real estate investors what it has already done, not just what it says it can do. Most DSCR lenders have closed hundreds of rental property loans, and rescued files other lenders declined. Almost none of that work is visible online. The investor comparing lenders sees a rate sheet, a logo, and a contact form — not the thin-ratio file you restructured into an approval, or the six-property portfolio you refinanced in one close.
That is the gap between earned credibility and market visibility in its plainest form. AuthorityLogix documented how it closed that gap on its own build in a platform case study, and the principle carries straight into lending: proof that is written down, structured, and published works for you every day. This article covers how to build DSCR lender case study content that proves expertise, stays inside compliance lines, and reaches the investors and brokers who decide where files go.
Why DSCR Lender Case Study Content Proves Expertise
Investors buying rental property do not choose a DSCR lender the way a first-time buyer chooses a mortgage. They are repeat borrowers. Their real question is whether this lender understands deals like theirs. A rate quote cannot answer that. A documented deal can.
Research on proof content backs this up across B2B markets. In the Content Marketing Institute’s B2B benchmarks report for 2025, 53% of marketers said case studies and customer stories produced their best results, and 75% had used them in the previous 12 months, according to CMI research. Demand Gen Report’s 2025 Demand Generation Benchmark Survey adds a second signal: 57% of respondents chose case studies as their top content format.
The market has also grown more crowded. Optimal Blue data reported by HousingWire in September 2026 shows DSCR and investor lock volume grew 130% from January 2022 to August 2026. More lenders now compete for the same investors, and most describe their programs in identical language. DSCR lender case study content breaks that sameness, and it gives search engines something specific to rank — a point the SEO playbook develops for lenders who want to be found before the competition.
Case studies also do a job a program page cannot: they show judgment. A program page says you lend on short-term rentals; a breakdown shows how you handled a property with nine months of booking history and a seasonal income dip. That is why the financial services hub treats proof content as core lender infrastructure rather than an occasional marketing piece.
The Financial Services Content System lays out the compliance-aware publishing blueprint that DSCR lender case study content plugs into.
DSCR Deal Case Study Marketing: The Anatomy of a Deal Breakdown
DSCR deal case study marketing works when every breakdown follows the same structure. Investors learn to read the format, your team can produce it quickly, and nothing important gets left out. The six-part structure below is the one we recommend for DSCR lender case study content because it mirrors how an investor actually evaluates a deal.
| Breakdown Section | What It Shows the Investor | Illustrative Detail |
|---|---|---|
| Investor Scenario | Who the borrower is, without identifying them | Self-employed investor with three existing rentals |
| Property Profile | Asset type and market context | Two-family property in an outer-borough neighborhood |
| The DSCR Math | How rent was measured against the full housing payment | Market rent from the appraisal, ratio shown as a range |
| The Obstacle | Why the file was hard to place | One vacant unit at application, limited rent history |
| The Structure | What your team did to solve it | Lease-up documentation and an adjusted loan amount |
| The Outcome | What closed, stated factually with no promises | File closed and the investor returned for a second property |
Why the Ratio Belongs in Every Piece of DSCR Lender Case Study Content
The ratio is the part investors care about most and the part most lenders leave out. Showing how gross rent was compared against principal, interest, taxes, insurance, and association dues teaches the reader how you underwrite. It also signals that you will explain your decisions on their file instead of hiding behind a yes or a no.
Brokers read DSCR lender case study content differently from investors. They are looking for a lender that will take the hard files they cannot place elsewhere, and a published breakdown tells them which scenarios you are comfortable with before they pick up the phone. That makes each case study a quiet piece of broker marketing that works without a sales call.
Format consistency also lets the breakdowns stack. Ten case studies that share one structure can be grouped by property type, by obstacle, or by market, and each group becomes a page investors can browse. Organized that way, DSCR lender case study content stops being a series of posts and becomes part of an educational hub that answers the question every investor brings: has this lender done a deal like mine?
Mortgage Lender Proof of Expertise Content Under Compliance Rules
Mortgage lender proof of expertise content carries risks that a software testimonial does not. You are describing a real borrower’s financing. None of this is legal guidance, and your compliance team or counsel has the final word. What follows are the marketing guardrails that keep DSCR lender case study content publishable.
A Pre-Publication Checklist for Deal Stories
- Get written borrower consent before any deal is described publicly, even in anonymized form.
- Remove names, addresses, and any detail that could identify the borrower or the property.
- Round figures or use ranges where exact numbers are not needed to make the point.
- Keep rates, payment amounts, and down payment figures out unless compliance has approved the required disclosures.
- Describe what happened on one file, never what a reader should expect on theirs.
- Route every draft of DSCR lender case study content through the same compliance review your other advertising receives.
The rate-and-payment point matters most. Under Regulation Z, the CFPB’s advertising rule at 12 CFR 1026.24 treats terms such as a down payment amount, the number of payments, a payment amount, or a finance charge as triggering terms that require additional disclosures, including the annual percentage rate. Many DSCR loans are business-purpose credit, but whether a particular rule applies is a compliance question, not a marketing one. The safest story is built on ratios, property facts, and problem-solving rather than pricing.
Compliance review is also easier when DSCR lender case study content lives inside a defined structure. If every breakdown follows the same template and links back to the same set of pillar pages, reviewers see the same fields each time and can approve faster. The template becomes a compliance asset as much as an editorial one.
This is where most lenders stall. They collect two good stories, wait months for approval, and then stop. A repeatable process — intake form after closing, consent request, anonymization pass, draft, review, publish — removes that bottleneck, and it is exactly the kind of workflow that well-built content systems run so proof keeps flowing without the loan team writing it.
Not sure whether your closed deals are working as proof yet? The FS Authority Gap Assessment shows where your expertise is invisible and what to build first.
DSCR Lender Deal Breakdown Content That Investors Share
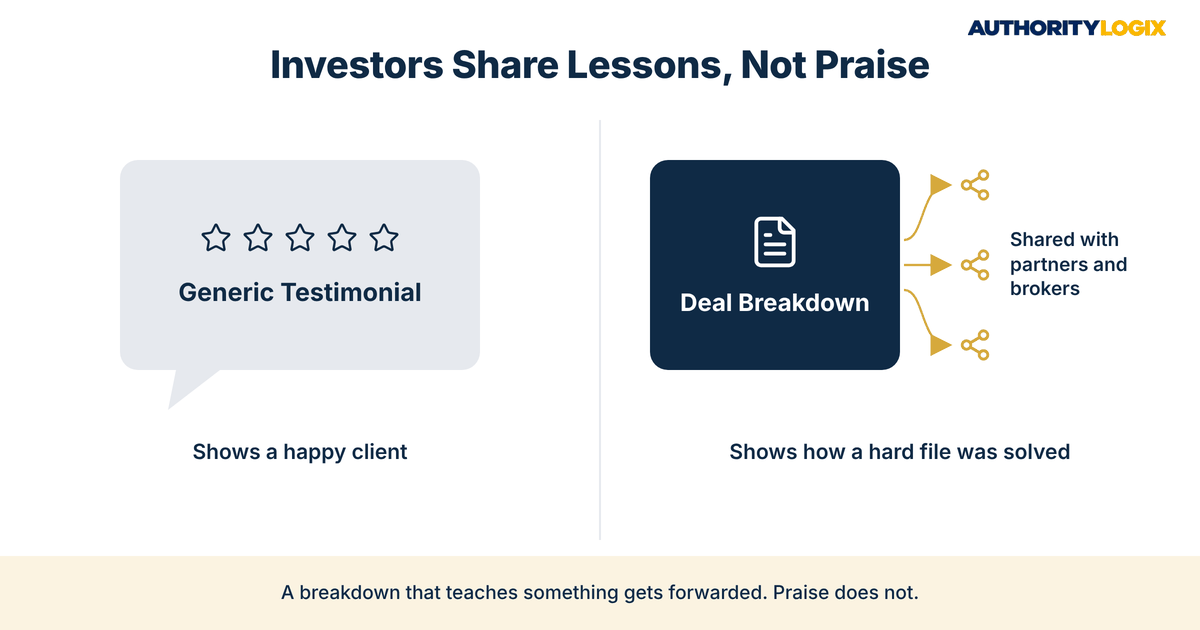
DSCR lender deal breakdown content gets shared when it teaches something. Investors pass a breakdown to a partner, post it in an investor group, or forward it to their broker because it explains a situation they expect to face. A story that only says the lender was responsive and the closing was smooth gives them nothing to pass along.
| Element | Generic Testimonial | Deal Breakdown |
|---|---|---|
| What it proves | The client was happy | The lender solved a specific problem |
| What an investor learns | Nothing about their own deal | How a similar file was structured |
| Search value | Little, with no specific terms | Matches scenario searches, such as a DSCR loan with a vacant unit |
| Shareability | Low | High, because partners and brokers can use it |
| Role in DSCR lender case study content | Supporting quote at most | The core format |
Shareable DSCR lender case study content almost always names the lesson. One breakdown might explain why a short-term rental needed twelve months of booking data; another shows why a portfolio refinance moved faster as one blanket loan than as five separate files. That kind of specific teaching is the trust signal the authority guide describes as the line between visible firms and invisible ones.
Loan officers know the deal but rarely have time to write it, and generic writers know the format but not the underwriting. The answer is a short interview with the originator after closing, turned into a draft by someone who understands both, which is the core of what finance content development is for. The originator spends 20 minutes; the lender gets an asset that keeps working.
Expertise is the asset. Good DSCR lender case study content simply puts that expertise in a form an investor can read late at night while comparing three lenders side by side.
Distributing Case Studies to Investors and Brokers
Publishing a breakdown is half the job. DSCR lender case study content earns its keep when it reaches the people deciding where the next file goes — active investors, the brokers who serve them, and the search engines both groups use. Each channel needs the same story in a slightly different shape.
- Search: a full breakdown page targeting the scenario an investor would type into Google.
- Email: a short summary sent to past borrowers and broker partners, pointing to the full page.
- LinkedIn: a three-paragraph version focused on the obstacle and the fix.
- Broker kit: a one-page version brokers can share with their own clients.
Every one of those channels should point back to a page with a clear next step. A reader who just finished a breakdown is a warm prospect, so offer a scenario review rather than a generic contact page. That handoff is what turns proof into pipeline, and it is the job of the wider lead system sitting underneath the content.
Syndication extends reach further. When a breakdown is repurposed into industry articles and guest posts, it builds the third-party signals that tell search engines and AI tools your firm is a credible source on DSCR financing. That process is what authority distribution covers, and it multiplies the value of every piece of DSCR lender case study content your compliance team approves.
This approach is not theoretical. BKDSCR.com, the AuthorityLogix proof-of-concept in the NYC outer-borough DSCR niche, was built with 18 pillar pages, 7 interactive investor tools, and 48 SEO-optimized blog posts, and it generates inbound investor leads with zero paid ads.
DSCR Lender Case Study Content Mistakes That Undermine Credibility
Most lenders who try DSCR lender case study content make the same handful of errors. Each one is fixable, and each one explains why a lender with real expertise can publish proof content and still see no inquiries from it.
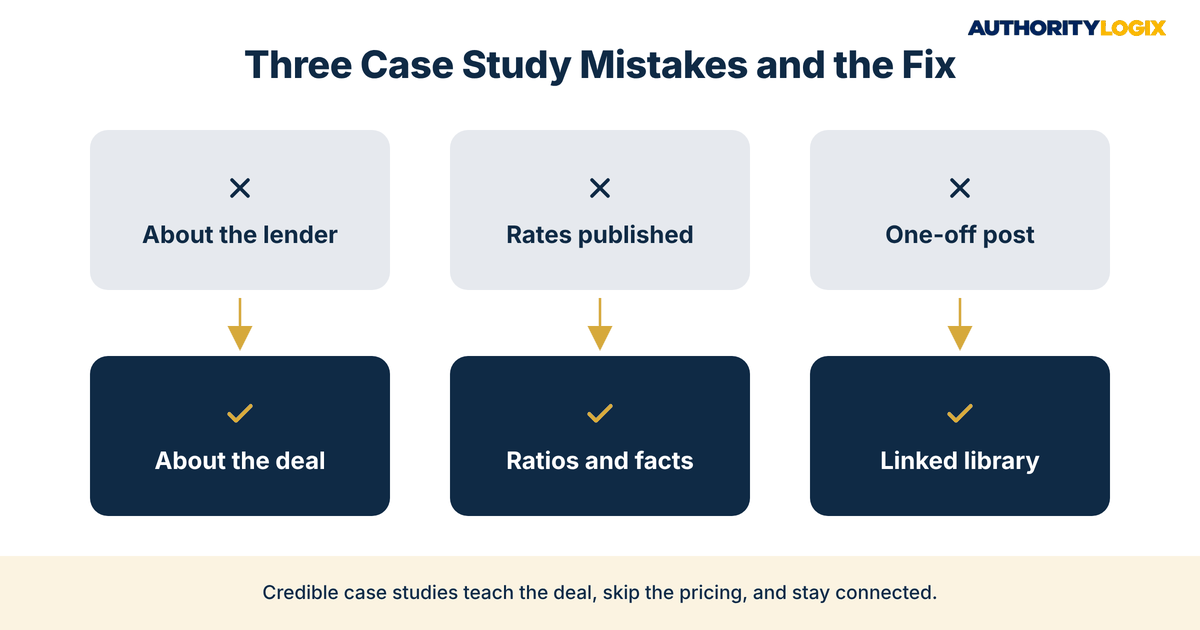
Mistake: Writing the story about the lender instead of the deal
DSCR lender case study content that spends three paragraphs on your team’s responsiveness reads as an advertisement. Investors want the scenario, the math, and the fix, with the lender’s role shown through decisions rather than adjectives. Breakdowns written that way also convert better, because the reader recognizes their own deal and takes the next step that your lead generation infrastructure puts in front of them.
Mistake: Publishing pricing that has not been through compliance
Rates and payment figures date quickly and can trigger disclosure requirements. Ratios, property facts, and timelines tell the story just as well and stay accurate far longer.
Question: How much DSCR lender case study content does a lender need?
There is no fixed number, but a library of 10 to 12 breakdowns covering your most common scenarios gives investors and search engines enough to recognize a pattern. One per month is a realistic pace once the intake process exists. Building that intake-to-publish workflow is part of what we do at the start of a content engagement.
Question: Can a case study cover a difficult or restructured file?
Yes, if it is handled carefully. A breakdown that explains why a file needed restructuring, and what the investor did to qualify, often teaches more than a clean approval, as long as the borrower consents and the story stays factual.
Mistake: Treating DSCR lender case study content as one-off posts
A breakdown published once and never linked again fades within weeks. Connected to program pages, grouped by scenario, and refreshed when guidelines change, the same piece keeps ranking and keeps getting forwarded. That connected approach reflects how we build every content library, where each piece has a defined role.
Ready to turn closed DSCR deals into proof that wins new investors? We’ll build case studies that show how you solve real deals.
Deals Explained Are Deals Remembered
The honest assessment is this: most DSCR lenders already have the deals that would make them the obvious choice for a certain kind of investor. They just have not written them down. A steady library of DSCR lender case study content is how that history becomes market position, and it is one of the slower, compounding moves the growth playbook treats as foundational for financial firms.
DSCR lender case study content will not replace referrals overnight, and they will not rescue a lender with weak service. What they do is make real expertise visible to people who have never heard of you. The approach comes from the same build AuthorityLogix ran on its own platform, which is why it works in competitive lending markets.
If you have closed the deals but the market still sees a rate sheet, the gap is infrastructure, not expertise. The deals are already done; the remaining work is turning them into DSCR lender case study content investors can find, read, and share. When you are ready to build that, the place to start is work with us.