Key Takeaways
- Mortgage company multi-market scaling usually fails on visibility, not capacity — the new office opens, but the borrowers in that market cannot find it.
- Google ranks local results mainly on relevance, distance, and prominence, so the authority earned in your home market does not transfer to a branch two hundred miles away.
- Every staffed office needs its own verified Business Profile, its own market pages, and its own review history — Google allows one profile per location and excludes virtual offices.
- BrightLocal’s 2026 Local Consumer Review Survey found 47% of consumers will not use a business with fewer than 20 reviews, which sets a practical floor for every new branch.
- Centralize the brand, the compliance review, and the educational hub; localize the profile, the pages, the reviews, and the partner relationships.
- Sequence is the whole game: prove local authority in one new market before opening the next, so mortgage company multi-market scaling compounds instead of diluting.
Table of Contents
Why Mortgage Company Multi-Market Scaling Breaks Local Authority
Mortgage company multi-market scaling usually starts with a strong home office — a team that has closed loans in one metro for years and owns the local searches there. Then the second office opens, and the inbound leads that flow so easily at home never show up in the new market. That gap is not a talent problem. The expansion simply moved faster than the firm’s local SEO footprint could follow.
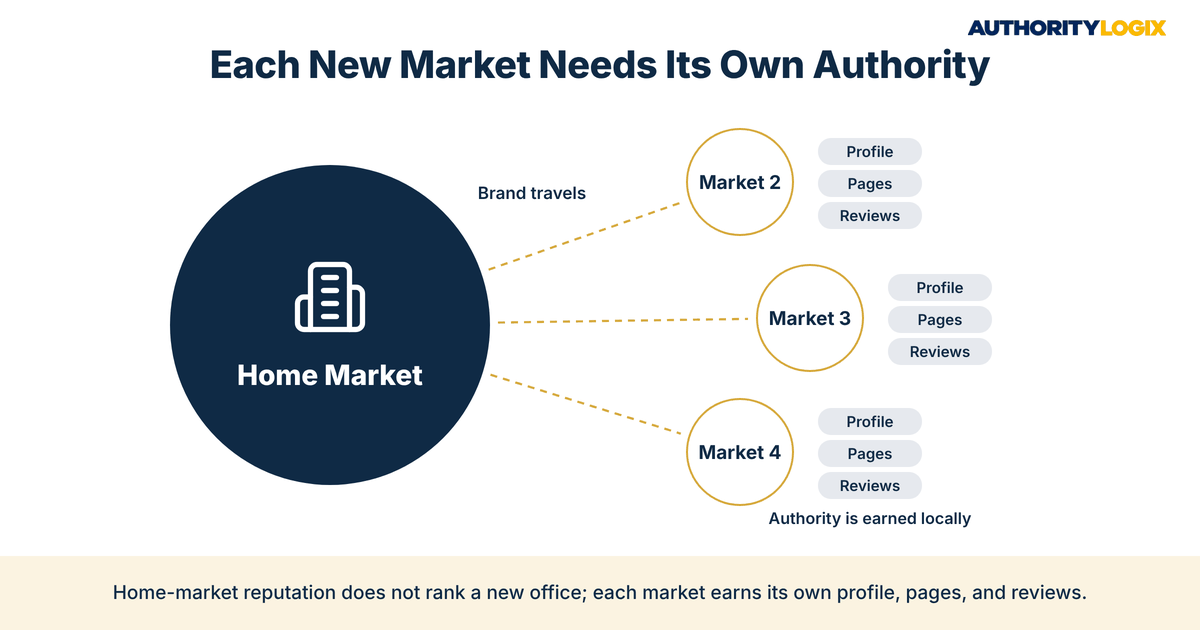
Google states that local results are based mainly on relevance, distance, and prominence — how well-known a business is, judged partly through reviews and links from other websites. Distance is the one factor no amount of home-market reputation can override. A borrower searching in the new market is shown lenders that are close, relevant, and already known there, which means fifteen years of credibility at headquarters count for very little two hundred miles away.
The firm is licensed, experienced, and respected, yet in the new market it looks like a newcomer with no history. Every element of trust has to be rebuilt locally, a principle the authority guide covers for firms entering skeptical markets. Mortgage company multi-market scaling works only when that rebuild is planned before the lease is signed.
The pattern repeats across every financial services segment we see. Lenders and advisory firms that expand by footprint alone end up with offices that depend entirely on the loan officers they hired and the referral relationships those people bring with them. Replacing that dependence with infrastructure is the thread running through everything on our financial services hub, and it is the difference between an office that produces and an office that waits.
The Financial Services Growth Playbook lays out the growth framework behind mortgage company multi-market scaling — how lenders, advisors, and firms build authority that compounds in every market they enter.
Lender Multi-Location Authority Strategy: One Brand, Many Markets
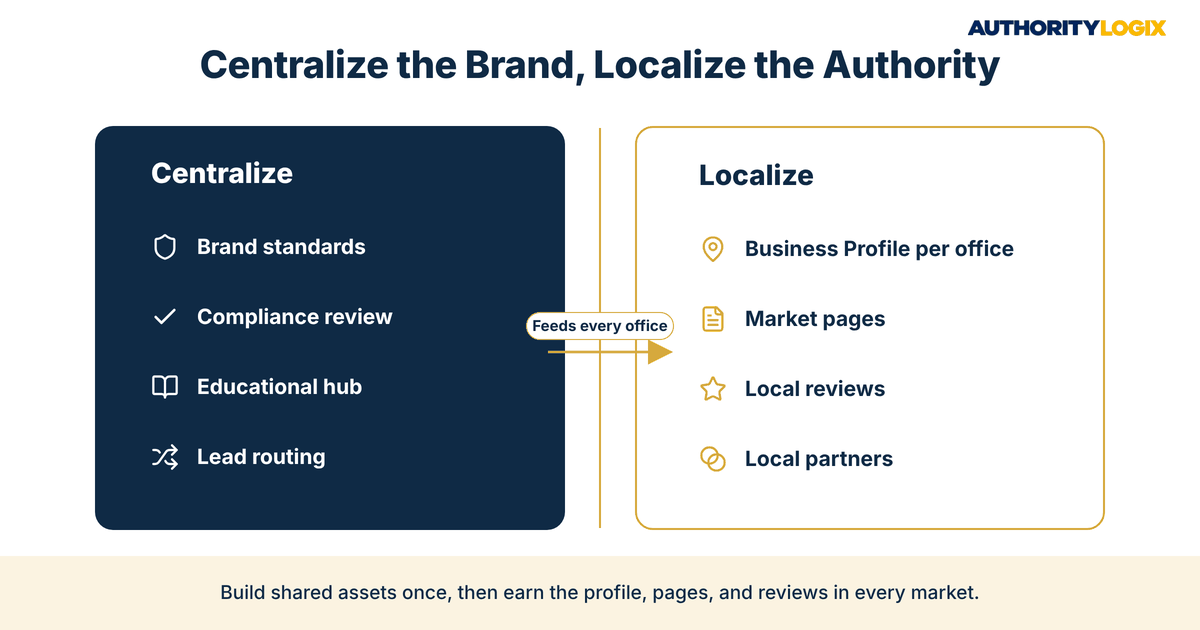
A lender multi-location authority strategy is the backbone of mortgage company multi-market scaling, and it starts with one decision: which assets belong to the brand, and which belong to each market. Get that split wrong and you either build a dozen disconnected mini-websites or one national site that ranks nowhere in particular. Get it right and every new office inherits the brand’s credibility while earning its own local proof.
What Mortgage Company Multi-Market Scaling Centralizes and What It Localizes
The split below is the framework we use when mapping mortgage company multi-market scaling for a lender planning its next two or three offices. Centralized assets are built once and maintained by one team. Localized assets are built per office and owned by the people working that market.
| Asset | Centralize or Localize | Why It Matters |
|---|---|---|
| Brand standards and messaging | Centralize | One voice keeps every office recognizable |
| Compliance review workflow | Centralize | One approval path for every page and post |
| Educational hub and loan program guides | Centralize | Topical authority accumulates on one domain |
| Google Business Profile | Localize | One verified profile per staffed office |
| Market pages and local content | Localize | Relevance to each city’s actual searches |
| Reviews and local partner relationships | Localize | Prominence is earned market by market |
Google’s own guidelines make the profile side of this non-negotiable. Each location gets one profile, the office must be reachable in person during its stated hours, and a rented mailing address where no one works is not eligible. Before any branch profile goes live, walk through the GBP setup steps so categories, hours, and licensing details match across every office.
The centralized side matters just as much. When loan program guides, DSCR explainers, and first-time buyer resources live in one educational hub on the main domain, every new market page can link into proven content instead of starting from zero. That is how mortgage company multi-market scaling gets a head start: a new office on an established domain ranks faster than a standalone site ever could.
Mortgage Company Growth Scaling With Market-Specific Content
Mortgage company growth scaling breaks down when the content plan treats every market as interchangeable. A page with a new city name in the title but the same paragraphs as the home market page gives Google no reason to rank it. Google’s spam policies name pages targeted at specific regions or cities that funnel users to one page as a doorway pattern, and cloned city pages fit that description closely.
Market-specific content means writing about what is actually different in each place: property types, price bands, local first-time buyer programs, the neighborhoods investors target, and the questions loan officers hear every week in that office. A market page built on that material reads as local because it is local. This is also where long-term positioning gets decided, since the topics an office owns in its first year shape what it can rank for in its third.
The workload multiplies with each office, which is why it needs a production model rather than heroic effort. Loan officers supply the local insight in short interviews, a central editor turns it into compliant pages, and one review workflow approves everything. Without content systems like that, the third office in a mortgage company multi-market scaling plan rarely gets its pages written at all.
The economics make the case for doing this well. The Mortgage Bankers Association’s August 2026 forecast projects $1.434 trillion in purchase originations out of $2.147 trillion in total 2026 volume, and purchase borrowers are the local, research-heavy segment that market pages serve. MBA’s second-quarter 2026 performance data put average production expenses at $10,936 per loan against a net production profit of $973, figures reported by HousingWire. With margins that thin, mortgage company multi-market scaling cannot rely on buying every lead a new office needs.
Market-specific content also gives each office something to send. Loan officers share a local page with a referral partner, a realtor links to it from a listing, and a borrower forwards it to a spouse. In mortgage company multi-market scaling, those small, repeated uses are how a new office starts to look established in its market.
Not sure whether your current visibility can support mortgage company multi-market scaling? The FS Authority Gap Assessment shows where your local authority is strong and where a new office would start from zero.
Financial Firm Regional Expansion Strategy and Sequencing
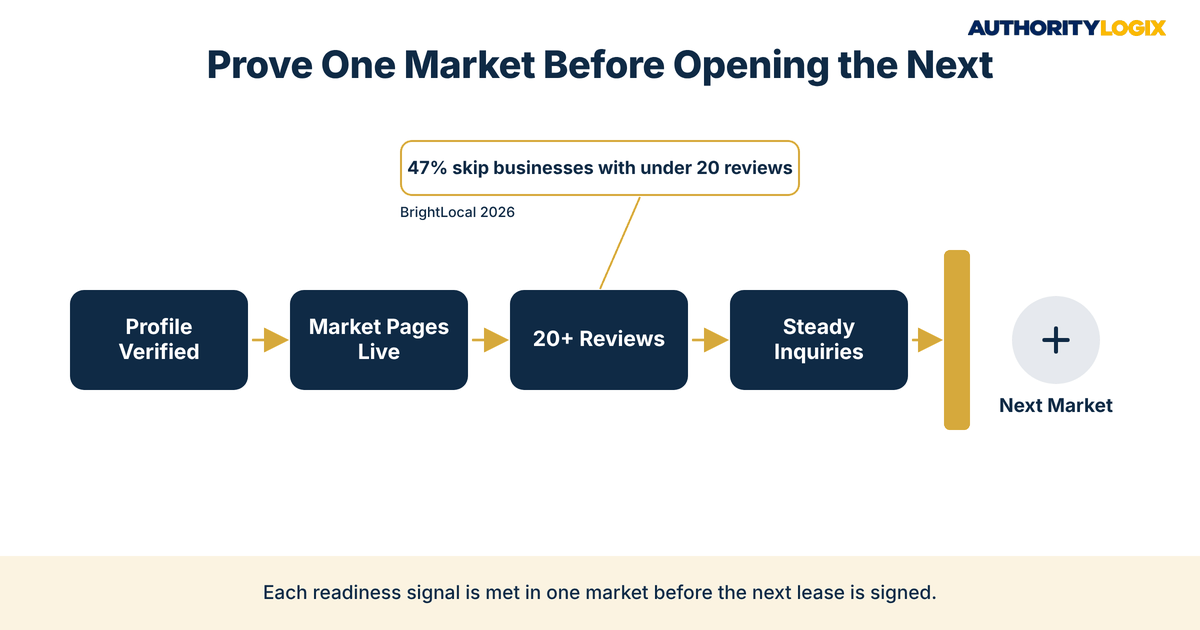
A financial firm regional expansion strategy is mostly a sequencing problem, and mortgage company multi-market scaling is where a poor sequence shows first. Opening three markets in one quarter splits the content team, the review requests, and leadership attention across three cold starts at once. Opening one, proving it, and then opening the next lets each market borrow the systems, templates, and lessons of the one before it.
The search side of that sequence follows the same order every time: technical foundation, then market pages, then the content cluster, then distribution. Each step is laid out in the SEO playbook, and skipping one shows up later as pages that are indexed but never rank. Mortgage company multi-market scaling rewards patience at this stage more than at any other.
The Readiness Test Before the Next Market Opens
Before the next lease is signed, the current new market should clear five signals. None of them guarantees results, but each one shows that local authority is forming rather than assumed.
| Readiness Signal | Target Before the Next Launch | Why It Matters |
|---|---|---|
| Verified Business Profile | Live, complete, categories matched to the office | Required to appear in local map results |
| Review count | 20 or more reviews on the office profile | 47% of consumers skip businesses with fewer than 20 |
| Review recency | New reviews arriving every month | 74% look for reviews written in the last three months |
| Market pages | Original pages for each core loan type | Earns relevance and avoids doorway patterns |
| Local inquiries | Steady inbound leads from search | Proof the market is producing, not just listed |
The review thresholds come from BrightLocal’s 2026 Local Consumer Review Survey, which also found that 97% of consumers read reviews for local businesses. For mortgage company multi-market scaling, that means a review request process should run from the first closed loan, not get added after the office feels established. Pair it with finance content written for that market’s borrowers, and the office builds prominence and relevance at the same time.
Distributing Authority Into Each New Market
Publishing market pages is half the job. Prominence — the third part of Google’s local ranking — depends on how well-known a business is, and that comes from mentions, links, and citations from sources the new market already trusts. A brand-new office has none of those on day one, and most mortgage company multi-market scaling plans never budget for building them.
Distribution closes that gap deliberately. Each market gets its own plan: features with local real estate partners, community and chamber listings, regional media placements, and syndicated versions of educational articles that point back to the market page. A single content system decides what gets distributed and when, so the effort stays consistent across every office instead of depending on who has time that month.
AI search has made this layer more important, not less. BrightLocal’s 2026 survey found 45% of consumers now use ChatGPT or other AI tools for local recommendations, up from 6% a year earlier, while Google’s share as a review source fell from 83% to 71%. AI answers draw on the same signals — consistent citations, recent reviews, and credible mentions — which is why authority distribution has to be built per market rather than once for the whole company.
Mortgage company multi-market scaling that skips distribution produces offices that are technically visible and practically unknown. The pages exist and the profile is verified, but nothing outside the firm’s own domain says the office matters. Borrowers notice that silence before Google does.
Mortgage Company Multi-Market Scaling Mistakes That Dilute Local Rankings
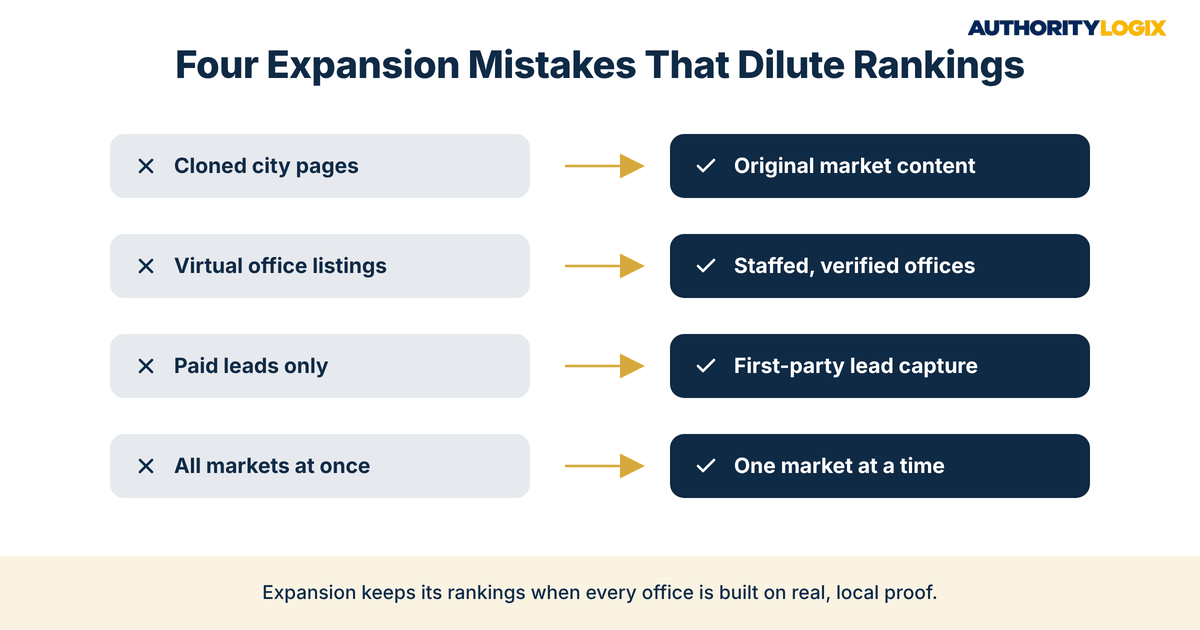
Most expansion problems are visible within the first six months, and most are avoidable. These are the mistakes and questions that come up most often when lenders plan mortgage company multi-market scaling. Each one looks reasonable in a planning meeting and expensive twelve months later, which is why mortgage company multi-market scaling deserves a written plan before the first new hire.
Mistake: cloning the home market page for every new city
Swapping a city name into the same template is the fastest way to build pages that never rank. Google treats near-duplicate city pages as a doorway pattern, and borrowers notice generic copy just as quickly. Each market page needs original material drawn from that office’s loan officers and local deals.
Mistake: listing branches at virtual offices
An unstaffed suite or mailing address is not eligible for a Business Profile under Google’s guidelines, and a listing built on one puts the whole profile at risk. Open the profile when the office is staffed during stated hours. Until then, serve that market from the main site’s content and the nearest real office.
Can paid leads carry a new market until organic visibility arrives?
Paid leads can bridge the first months, but they stop the moment the budget does. With production expenses near $10,936 per loan in MBA’s second-quarter 2026 data, a branch that depends on purchased leads is renting its pipeline. First-party lead generation built into the market pages keeps producing after the bridge ends.
How long before a new market produces inbound leads?
There is no guaranteed timeline, because competition, market size, and the starting condition of the profile all vary. Most of the work in the first ninety days is foundation — the profile, the pages, the first reviews — and results follow that foundation rather than preceding it. Mapping that timeline for a specific market is part of what we do before any build begins.
Who should own each market’s content?
Loan officers own the insight, and the central team owns the production. Asking producers to write their own pages almost guarantees nothing gets published. A short monthly interview, edited centrally and approved through one compliance workflow, is how we build market content that stays current without pulling producers off their pipelines.
Planning to open your next market? We’ll build the local profile, pages, and reviews that let each new office produce inquiries sooner.
Mortgage Company Multi-Market Scaling: Scale the System, Not Just the Footprint
The firms that expand well treat each new office as another instance of a system they already proved, not a fresh experiment. Brand, compliance, and education are built once. Profiles, pages, reviews, and distribution are repeated per market from the same playbook, with one lead system capturing every inquiry and routing it to the right office.
That is the logic behind BKDSCR.com, the AuthorityLogix proof-of-concept. It was built for one defined market — NYC outer-borough DSCR investing — with 18 pillar pages, 7 investor tools, and zero paid ads, to prove that local authority can be built deliberately in a competitive market. The full record of why it works is there for any firm that wants to see the evidence before deciding.
The honest assessment: mortgage company multi-market scaling does not fail because the new market lacks borrowers. It fails because the firm arrives with credibility it cannot show yet and expects the home market’s reputation to travel on its own. It does not. Authority compounds, but only inside the market where it was built, so each office needs its own foundation before the next one opens. If that is the build you are planning, work with us to map the first market before the second lease is signed.